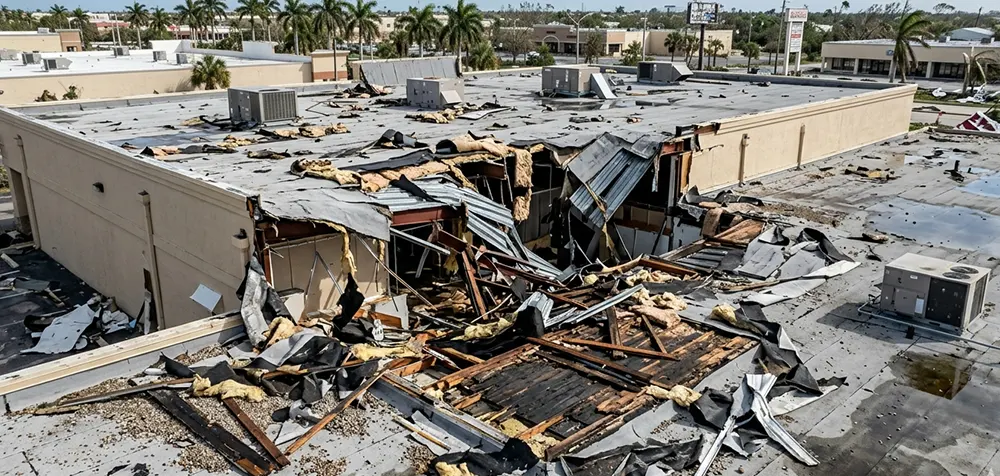
Your roof leaked after the storm. You filed a claim. Weeks later a letter showed up saying the damage was "wear and tear," not wind. Your roof is still broken. The check never came.
A hurricane roof damage claim denied in Miami is not the end of the claim. It is the insurer's opening position. Florida law gives you several ways to push back, and some of them cost nothing.
Here is how to read the denial, what to do in the next 30 days, and when a lawyer is worth calling.
Your denial letter has to explain itself. Read it closely.
Florida Statute 627.70131 sets a clock on your insurer. The company has 7 calendar days to acknowledge your claim. It has 30 days after your proof of loss to inspect the property. And it has 60 days to pay or deny.
The same law says a denial must come with a written explanation. The insurer has to point to the policy language it relied on, and tie that language to the facts.
So read the letter with two questions in mind. Which exact policy words did they quote? And what evidence did they use?
Vague letters are common. A denial that says only "the loss is not covered" does not meet the standard. That alone is worth raising.
Four reasons Miami roof claims get turned down
1. They blamed age instead of wind
This is the most common denial on Miami-Dade roofs. The adjuster writes "wear and tear," "deterioration," or "poor maintenance." Every one of those words points to an exclusion in your policy.
Age and storm damage can exist on the same roof. A 14-year-old tile roof can still be torn open by wind. The question is what caused the opening, not how old the tile was.
2. You reported it too late
Florida Statute 627.70132 gives you 1 year from the date of loss to report a new or reopened claim. You get 18 months for a supplemental claim. Those windows were cut down in December 2022. They used to be two and three years.
Many Miami homeowners still work off the old numbers. Check your storm date against the calendar today.
3. They called it pre-existing
Insurers compare your roof to old aerial photos or prior claim files. If a stain or a cracked tile shows up in an older image, they may argue the whole loss predates the storm.
Your own photos are the answer. Anything you shot before the storm carries real weight here.
4. The estimate came in under your hurricane deductible
Florida hurricane deductibles run 2%, 5%, or 10% of your dwelling coverage. On a $500,000 dwelling limit, 2% is $10,000 and 5% is $25,000.
If the adjuster writes your roof at $18,000 and your deductible is $25,000, you get nothing. So the fight is over the estimate, not over coverage. A low estimate and a denial can amount to the same outcome.

The matching rule most homeowners never hear about
Say wind took out 12 tiles on the front slope. The insurer offers to replace 12 tiles. The new tiles are a different color, because your tile line was discontinued nine years ago.
Florida Statute 626.9744 speaks to this. When replaced items do not match in quality, color, or size, the insurer has to make reasonable repairs or replacement in adjoining areas.
The statute is not a blank check. It lets the insurer weigh cost against remaining useful life. Even so, it gives you something to push with. Patch offers on discontinued tile are worth challenging.
Miami-Dade roofs cost more to fix, and that changes the math
Miami-Dade and Broward sit inside the High Velocity Hurricane Zone. The Florida Building Code sets a design wind speed of 175 mph in Miami-Dade. Broward is 170 mph.
HVHZ rules are stricter than the rest of the state. Every roof component needs a current Miami-Dade Notice of Acceptance. Self-adhered underlayment is required across the whole deck, rather than only the eaves and valleys.
A repair priced on standard Florida code will come in low for a Miami-Dade roof. If your carrier used an out-of-area estimating template, say so in writing.

What to do in the next 30 days
- Request your complete claim file in writing. Ask for the adjuster's report, all photos, and the estimate with line items.
- Get an independent roofer's inspection in writing. Ask the roofer to state the cause of damage and price the repair to HVHZ code.
- Pull every photo on your phone from before the storm. Check the date stamps.
- Save receipts for tarps, water extraction, and emergency repairs.
- Put every request in email. Phone calls leave no record.
Do not let your roof stay open while you argue. Policies require you to prevent further damage. Tarp it, keep the receipt, and photograph the work.
A free state program you can use before you sue
The Florida Department of Financial Services runs a residential property mediation program. A neutral mediator sits down with you and the carrier.
Three things worth knowing:
- The insurer pays the cost, not you.
- The dispute has to be at least $500 after your deductible.
- It is non-binding, so you keep every other option.
Call the DFS helpline at 1-877-693-5236 to start. Mediation works best on honest disagreements about scope or price. It works poorly when the carrier has taken a hard coverage position and will not move.
When a lawyer changes the outcome
Numbers make the point better than adjectives. Cernitz Law took on a Hurricane Ian claim where the carrier paid $89,000 and stopped. The case settled for $600,000.
On a Hurricane Irma file, the insurer paid $131,000 and refused to add a dollar. That claim closed at $750,000 after litigation.
A condominium hurricane claim was denied outright. The carrier paid nothing. After suit was filed, coverage was granted and the buildings recovered $5,500,000.
You can review more Cernitz Law case results before you decide anything.
Managing partners Justin Cernitz and Candise Shanbron both started out on the insurance side. Shanbron spent the first five years of her career representing carriers. That background shapes how the firm reads a denial letter.
Not every denial needs a lawsuit. Ask for a free review, then decide.
Questions Miami homeowners ask after a roof denial
Can I reopen a hurricane roof claim after it was denied?
Yes. A denial is the carrier's position. It is not a final ruling. You can send new proof, ask for state mediation, or file suit. Timing is the limit. Florida gives you 1 year from the date of loss to report a new or reopened claim. You get 18 months for a supplemental claim.
How long does my insurer have to pay or deny a claim in Florida?
60 days from notice of the claim, under Florida Statute 627.70131. The insurer also has 7 days to answer your letters. It has 30 days after your proof of loss to inspect the roof. A denial must come with a written reason tied to the policy.
My insurer says my roof is too old. Does that end the claim?
No. Age by itself is not an exclusion. What matters is what caused the damage. Get an outside roofer to put the cause in writing. That is the usual answer to a wear and tear denial.
Does my insurer have to match my existing roof tile?
Florida Statute 626.9744 calls for reasonable repair in adjoining areas when new items do not match in quality, color, or size. The insurer can still weigh what that costs against what it buys you. Patch offers on tile that is no longer made are often worth a fight.
What does a property damage attorney cost in Miami?
Most work on contingency. You pay nothing up front. The fee comes out of what the firm recovers. Cernitz Law reviews denied claims free and charges no fee unless it wins money for you.
Do not let the one-year clock run out
The deadline is the part people lose on. A hurricane roof damage claim denied in Miami can still be worth real money months later. It is worth nothing after the reporting window closes.
Cernitz Law handles hurricane damage claims in Miami and denied and underpaid claims across Miami-Dade on contingency. There is no fee unless the firm recovers for you.
Call (888) 683-2624 for a free case evaluation, or use the contact page. Bring the denial letter. That is where the read starts.
Cernitz Law handles denied and underpaid hurricane roof claims across Miami-Dade. There is no fee unless the firm recovers for you.
Call (888) 683-2624 - Free Case EvaluationNo fees unless we win. Available 24/7.