
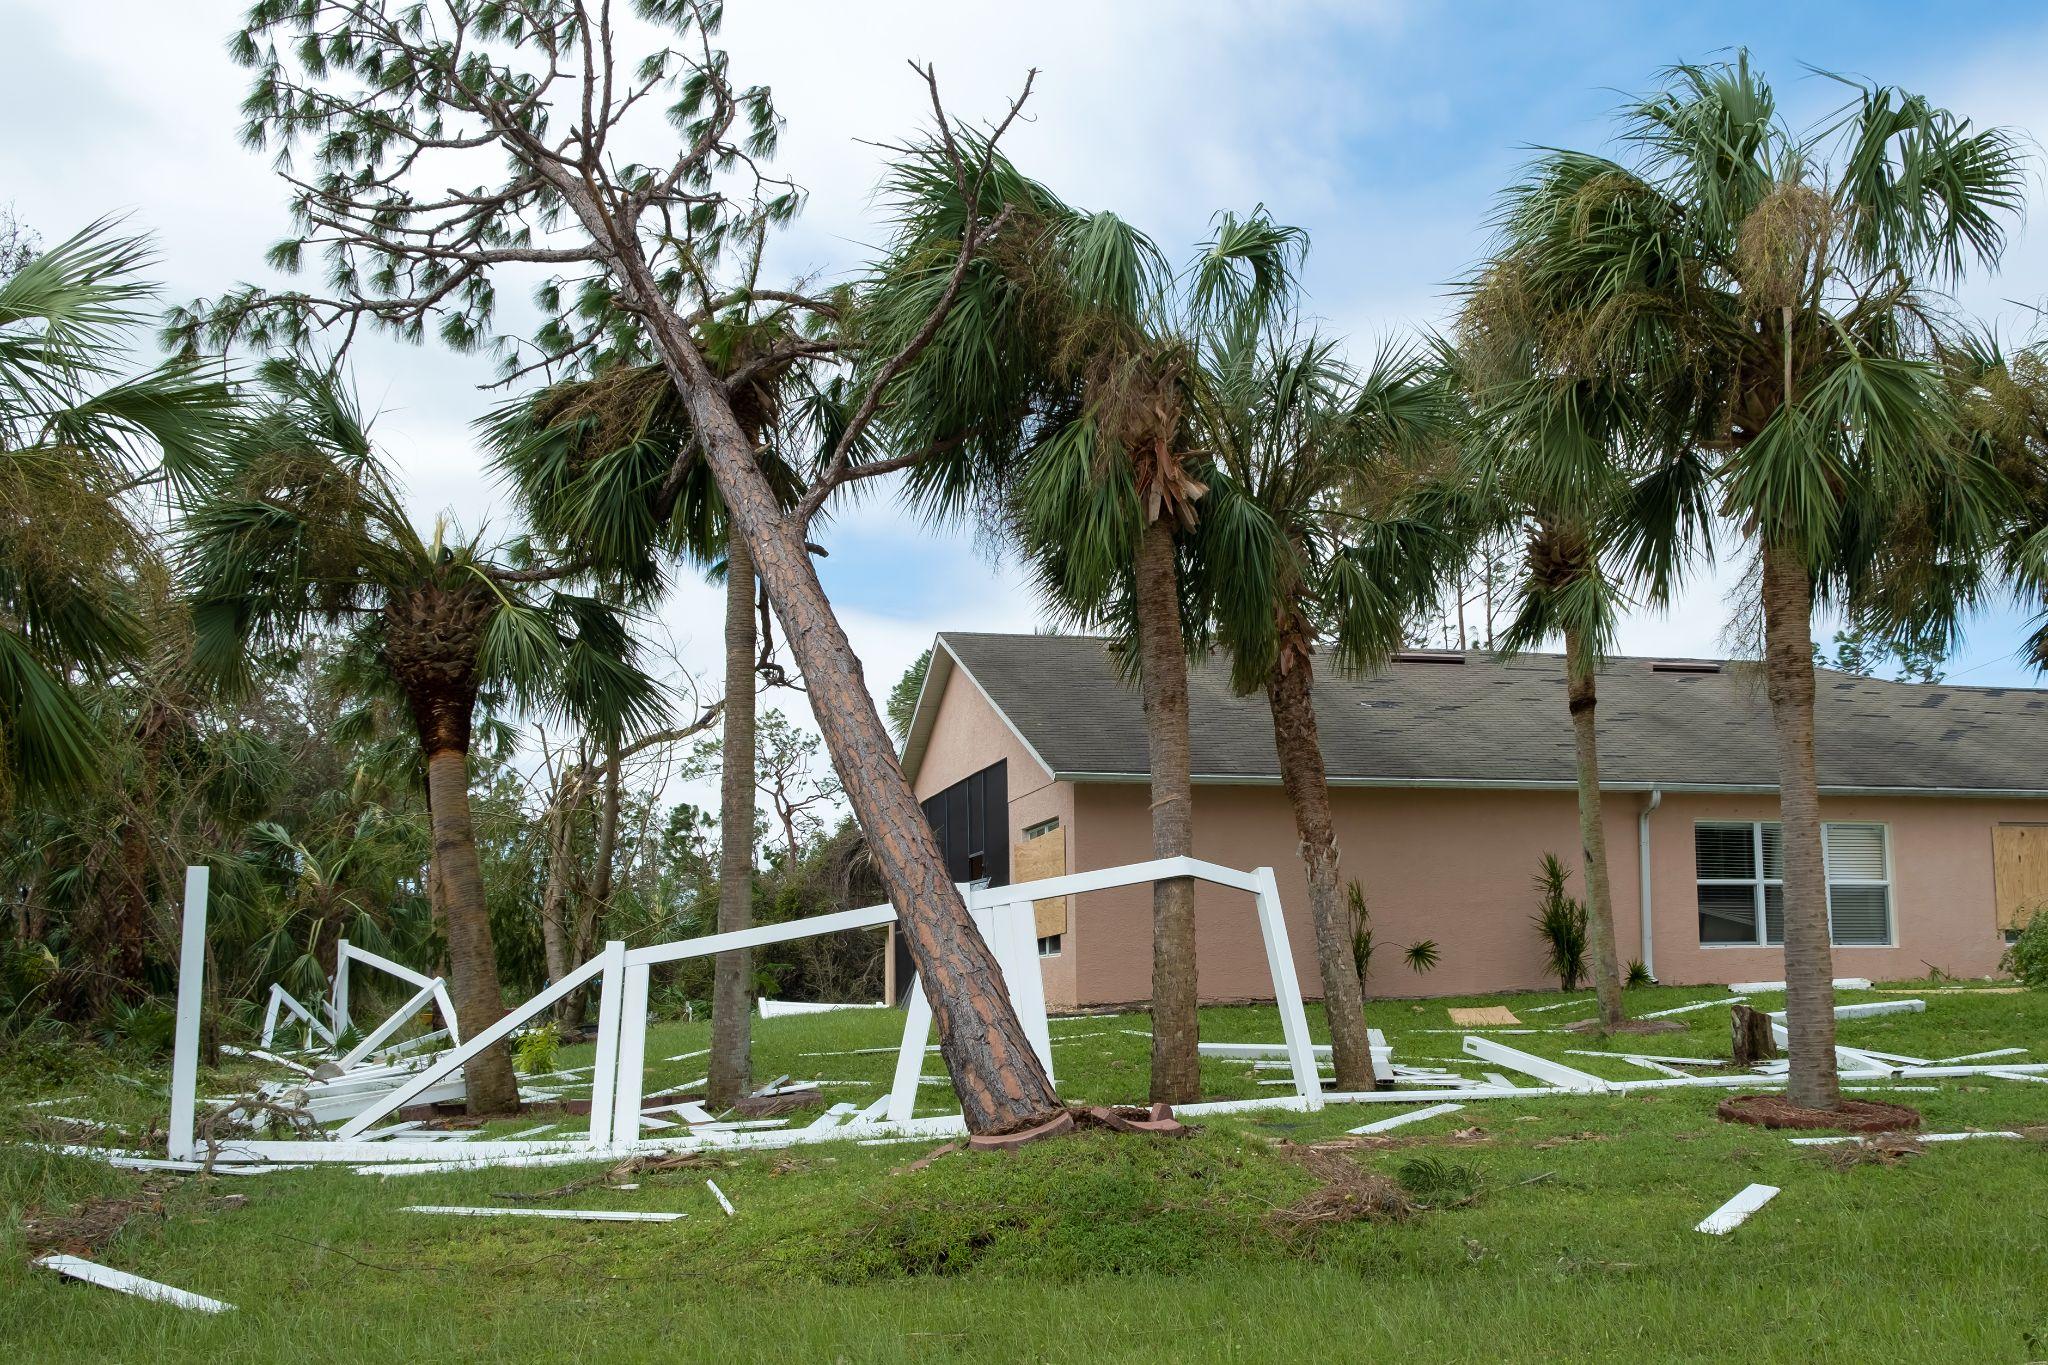
Cape Coral homeowners with unresolved Hurricane Ian claims still have legal options in 2026, but the window is narrowing. The deadline to file a new claim has passed, but disputed or denied claims can still be taken to court through 2027.
Hurricane Ian made landfall on September 28, 2022, carrying 155 mph winds directly over Cape Coral and Lee County. NOAA classified it as the costliest hurricane in Florida history, with $112 billion in damage across Southwest Florida. Almost four years later, roughly 20,000 Hurricane Ian claims across Lee, Charlotte, and Collier counties remained open or unresolved, according to reporting from WINK News. Heritage Insurance was fined $1 million by state regulators for mishandling Ian claims, and documented cases of systematic underpayment emerged across Cape Coral neighborhoods throughout 2023 and 2024.
If you are one of the Cape Coral homeowners still waiting on a fair resolution, this article explains what deadlines apply to your situation, what options remain in 2026, and what it takes to pursue a claim that was denied or underpaid.
What the Deadlines Actually Mean for Cape Coral Homeowners in 2026
Hurricane Ian occurred on September 28, 2022, which predates Florida's insurance reform legislation that took effect December 16, 2022. That distinction matters because the tighter deadlines created by that legislation do not apply to Ian claims. Cape Coral homeowners with Ian claims still fall under the older, more favorable timeline.
Here is where the deadlines stand as of August 2026.
Filing a brand new Ian claim: The deadline to file a new or reopened Ian claim was September 28, 2024, two years from the date of loss. That window has closed. If you experienced Ian damage and never filed a claim, pursuing a new one at this stage is no longer viable under most circumstances.
Filing a supplemental Ian claim: Supplemental claims for additional costs on damage previously disclosed to your insurer had a three-year deadline: September 28, 2025. That deadline has also passed for most situations.
Filing a lawsuit on an existing disputed claim: This is where many Cape Coral homeowners still have real options. Florida's five-year statute of limitations applies to Hurricane Ian claims under the older law. For Ian, that means legal action can be filed through September 28, 2027. If your claim was denied, underpaid, or you received a settlement that did not cover actual repair costs, you have roughly 14 months from today to file suit.
The practical takeaway: if you already filed a claim and the insurer denied it, underpaid it, or the dispute is still unresolved, the door to legal action is still open. If you never filed at all, your options are substantially more limited and a conversation with a property damage attorney is the first step to understand whether any path forward exists.
Why So Many Cape Coral Ian Claims Remain Unresolved
Cape Coral's geography and housing stock created a specific set of claim complications that drove unusually high dispute rates after Ian.
Wind vs. Flood Reclassification
Ian produced both extreme wind damage and significant storm surge flooding across Cape Coral's canal-laced neighborhoods. Standard homeowner policies cover wind damage. Flood damage falls under separate flood policies, typically through the National Flood Insurance Program, which carries different limits and different deductible structures.
Insurance companies hired independent adjusters who, in many documented cases, reclassified wind-driven damage as flood damage. The effect of that reclassification was to reduce or eliminate the homeowner's recovery under their primary policy and push the claim to a flood policy with lower limits. This tactic was one of the most common reasons Cape Coral homeowners received settlements far below their actual losses.
Anti-Concurrent Causation Clauses
Many standard homeowner policies contain anti-concurrent causation language. Under this clause, if a loss results from a combination of a covered peril, such as wind, and an excluded peril, such as flooding, the insurer can deny the entire claim rather than pay for the covered portion. Ian caused wind and flooding simultaneously across most of Cape Coral, which gave insurers an opening to invoke this clause and deny claims in full even when wind damage was clearly documented.
Florida courts have not uniformly upheld anti-concurrent causation denials, and a property damage attorney can evaluate whether a denial based on this clause was legally defensible in your specific situation.
Depreciation and ACV Disputes
Insurers calculate payouts using either Replacement Cost Value or Actual Cash Value. Policies that pay Actual Cash Value reduce the settlement by the depreciated value of the damaged materials. For a roof that was 15 years old at the time of Ian, an Actual Cash Value calculation could reduce the payout to a fraction of what replacement actually costs in the current Cape Coral construction market.
Many homeowners received Actual Cash Value settlements and did not realize their policy required them to complete repairs and submit proof before receiving the recoverable depreciation. That second payment, sometimes called the holdback, was never collected by homeowners who did not know to ask for it.
Lowball Estimates from Insurance Adjusters
Cape Coral sits in a market where post-Ian construction costs ran significantly higher than the national averages used by insurance company estimating software. The documented cases from WINK News reporting included a Lee County community where Heritage Insurance paid out approximately $250,000 on a claim that required well over $1 million in reconstruction costs. Cases like this were not outliers.
What "Unresolved" Looks Like in Practice
Cape Coral homeowners use the word "unresolved" to describe a range of situations, and the legal options differ depending on which applies.
Outright denial: The insurer reviewed the claim and denied coverage entirely, citing flood exclusions, anti-concurrent causation, or a determination that the damage did not meet the deductible threshold. A denied claim on a documented Ian loss is one of the strongest situations for legal action.
Underpayment with closed claim: The insurer paid something, the homeowner accepted the check, but the payout did not cover actual repair costs. Accepting an initial payment does not necessarily close out the right to pursue additional recovery, particularly if the full scope of damage was not accurately reflected in the original settlement.
Ongoing dispute with no resolution: The claim is technically still open, the insurer has not issued a final denial, but negotiations have gone nowhere for months or years. An attorney can send a formal demand that forces the insurer to act or face litigation.
Supplemental claim denied: Homeowners who filed supplemental claims before the September 2025 deadline and received a denial still have the ability to pursue those supplemental amounts through litigation before September 2027.
What Cape Coral Homeowners Should Do Right Now
Pull your claim file. Request a complete copy of your claim file from the insurer in writing. This includes adjuster notes, estimates, photographs, and all correspondence. You have a legal right to this documentation.
Get an independent repair estimate. If you have not already, get at least one written estimate from a licensed Cape Coral or Lee County contractor for the full scope of remaining damage or the amount the original settlement fell short. This becomes evidence in any legal proceeding.
Document current damage conditions. Photograph and video record all damage that has not been repaired. If you have been living with unrepaired Ian damage for nearly four years, that documentation carries weight.
Do not wait on the lawsuit deadline. The September 28, 2027 deadline for Ian litigation sounds like it is far away. It is not. Attorneys need time to evaluate the claim, build the case, and file before the window closes. Starting that process in the summer of 2026 still leaves a reasonable runway. Waiting until mid-2027 does not.
How Cernitz Law Handles Ian Claims in Cape Coral
Cernitz Law represents Cape Coral and Lee County homeowners on Hurricane Ian claims that were denied, underpaid, or are still unresolved. Managing partners Justin Cernitz and Candise Shanbron previously worked for insurance companies before founding the firm, which means they understand exactly how insurers build the case to minimize or deny hurricane claims from the inside.
The firm has recovered more than $250 million for clients across thousands of property damage cases throughout Florida. Cernitz Law works on contingency, meaning no upfront fees and no payment unless the firm recovers money on your behalf. Free case evaluations are available for Cape Coral homeowners who want to understand whether their unresolved Ian claim still has a viable path to recovery.
Frequently Asked Questions
Can I still file a Hurricane Ian claim in 2026?
The deadline to file a brand new Hurricane Ian claim was September 28, 2024, two years from the date of loss. That window has closed for most situations. However, if you already filed a claim that was denied or underpaid, you may still file a lawsuit through September 28, 2027 under the five-year statute of limitations that applies to pre-2023 hurricane losses.
My Hurricane Ian claim was denied. Do I still have options?
Yes. A denial from the insurer is not the end of the road. If your Ian claim was denied and the denial occurred on a policy in effect at the time of the storm, you have until September 28, 2027 to file a lawsuit. A property damage attorney can review the denial and assess whether the insurer's basis for refusing coverage was legally defensible.
The insurer paid something but it was not enough to cover my repairs. What can I do?
Accepting an initial settlement payment does not automatically close out your right to pursue additional recovery. If the original settlement did not reflect the full scope of damage, or if your policy included recoverable depreciation that was never paid out, a property damage attorney can evaluate what additional recovery may be available and whether the timeframe for pursuing it is still open.
What was the most common reason Hurricane Ian claims were denied in Cape Coral?
The two most frequently cited denial grounds in Cape Coral were wind vs. flood reclassification and anti-concurrent causation clauses. Insurers reclassified wind-driven damage as flood damage to shift costs to a separate, lower-coverage policy. They also used anti-concurrent causation language to deny entire claims when both wind and flood damage occurred simultaneously. Both of these denial approaches have been challenged successfully in Florida courts.
How do I know if my Ian settlement was fair?
Compare the settlement figure against an independent repair estimate from a licensed Lee County contractor. If the gap is significant, the settlement may have been calculated using national average pricing rather than actual Cape Coral market rates. Post-Ian construction costs in Southwest Florida ran well above national averages, and insurance estimates that used standard software pricing frequently came in far below what repairs actually cost in the local market.
What is the five-year statute of limitations and why does it apply to Hurricane Ian?
Florida reduced its property insurance statute of limitations to two years for losses occurring on or after March 24, 2023. Hurricane Ian occurred on September 28, 2022, which predates that change. Ian claims are therefore governed by the older five-year statute, giving policyholders until September 28, 2027 to file a lawsuit on an existing disputed or denied claim. This is a critical distinction from newer storm events, which have a much tighter legal window.
Conclusion
Nearly four years after Hurricane Ian, thousands of Cape Coral homeowners are still dealing with claims that never resolved fairly. The path forward depends on where each situation stands. Open disputes and denied claims are still actionable through September 2027, but that window requires action now, not next year.
The most important thing a Cape Coral homeowner with an unresolved Ian claim can do right now is get a professional evaluation of their specific situation. The insurer's final word is not always the legal final word, and the difference between a denied claim and a recovered claim often comes down to whether the homeowner had representation that understood how the insurer built its case.
Cernitz Law offers free evaluations for Cape Coral homeowners with unresolved Hurricane Ian claims. Contact us now to discuss what options remain before the 2027 deadline.
Cernitz Law represents Cape Coral homeowners facing denied and underpaid Hurricane Ian insurance claims. There is no fee unless we recover for you.
Call (888) 683-2624 - Free Case EvaluationNo fees unless we win. Available 24/7.